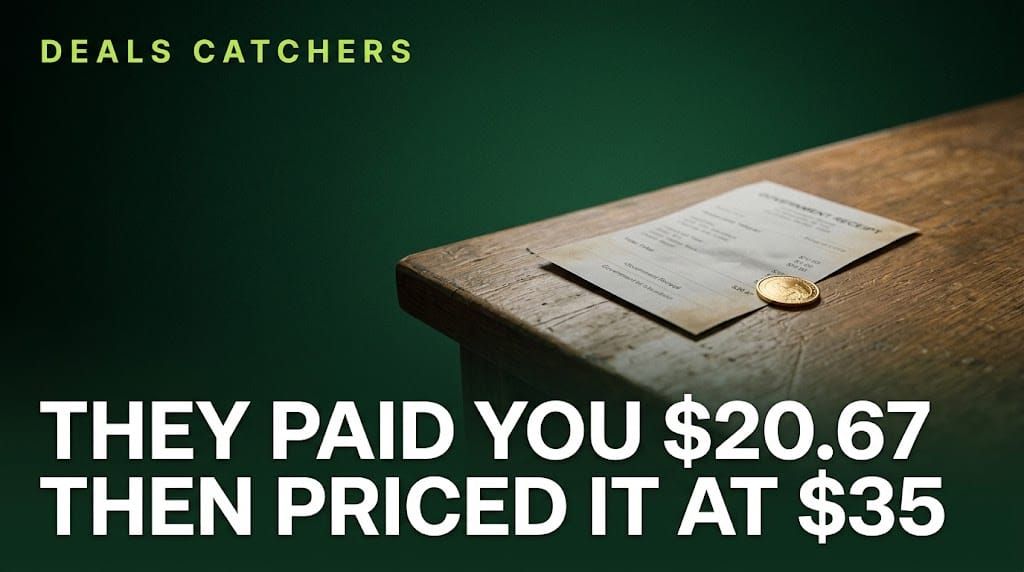
They Bought at $20.67. Then They Set the Price at $35.
 |
Deals Catchers • August 27, 2026
 By Mike Lee · 27 Aug 2026
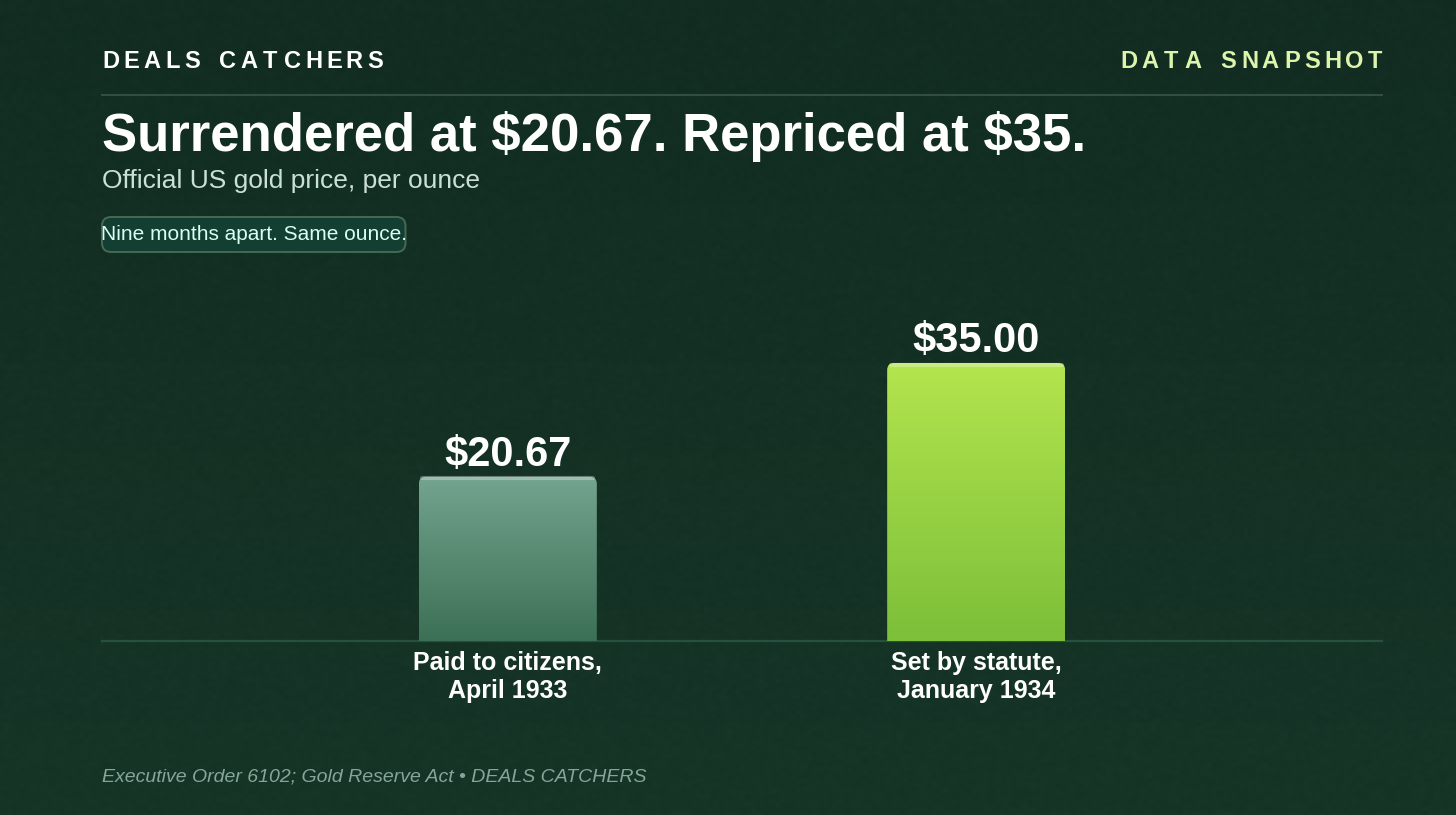
Americans handed over their gold at $20.67 an ounce. Nine months later the government priced the same ounce at $35 and kept the difference.
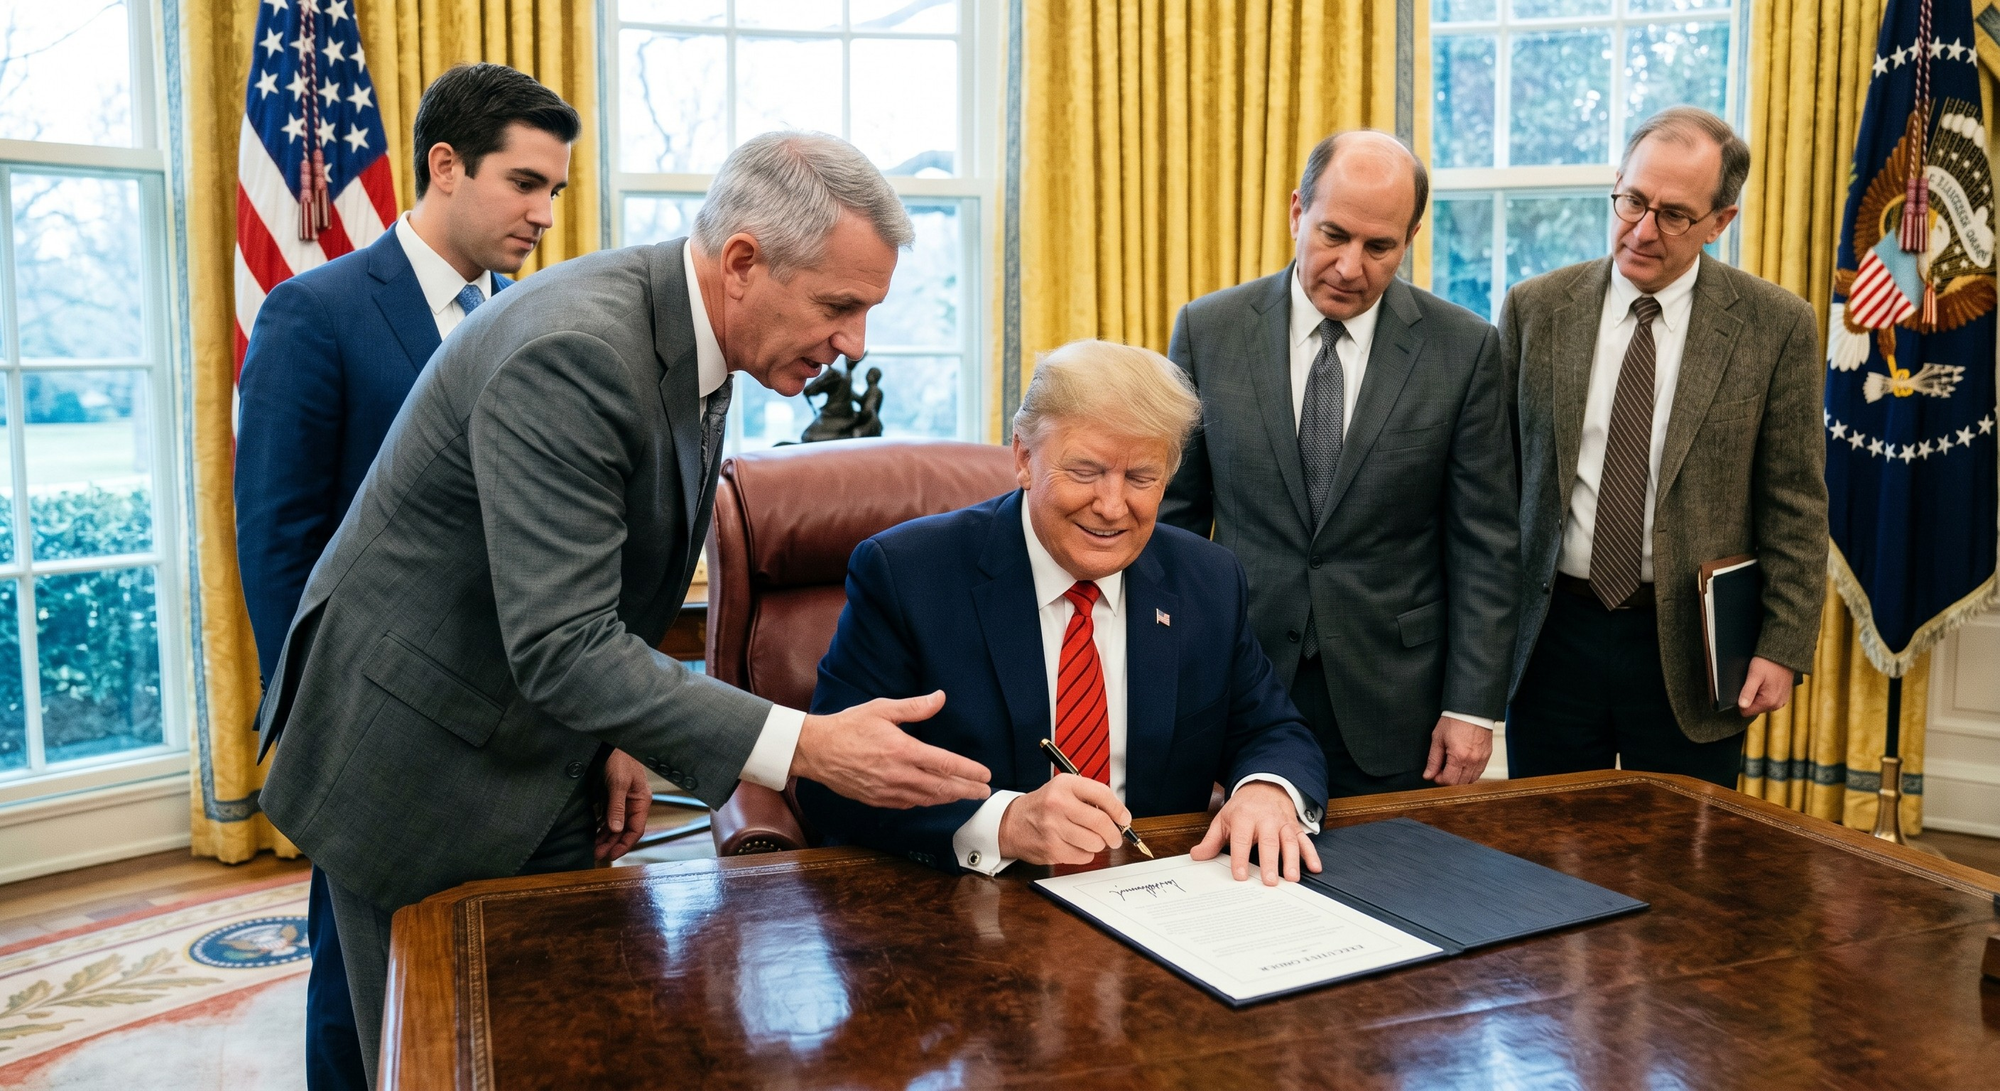
In 1934, the government executed a legal maneuver that transferred billions in wealth overnight. Send me the free report → Ad
| Latest Stories | See all → |
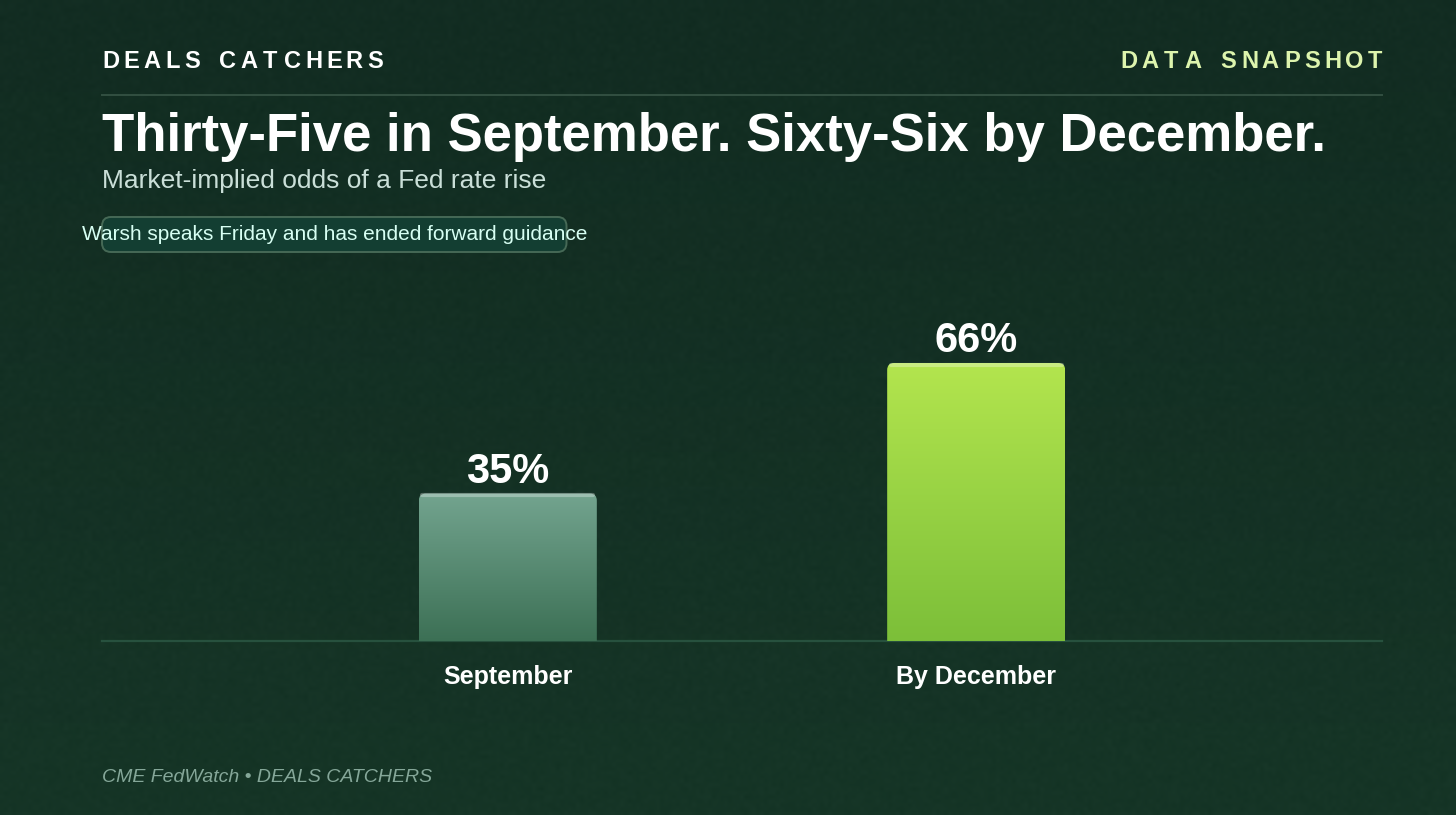
The people who moved early in 1934 didn’t have a warning. You do. Send me the free report → Ad
| The Week Ahead |
| Warsh speaks Friday morning at a symposium themed on payments, not rates. If he stays quiet on policy, the theme is the message. |
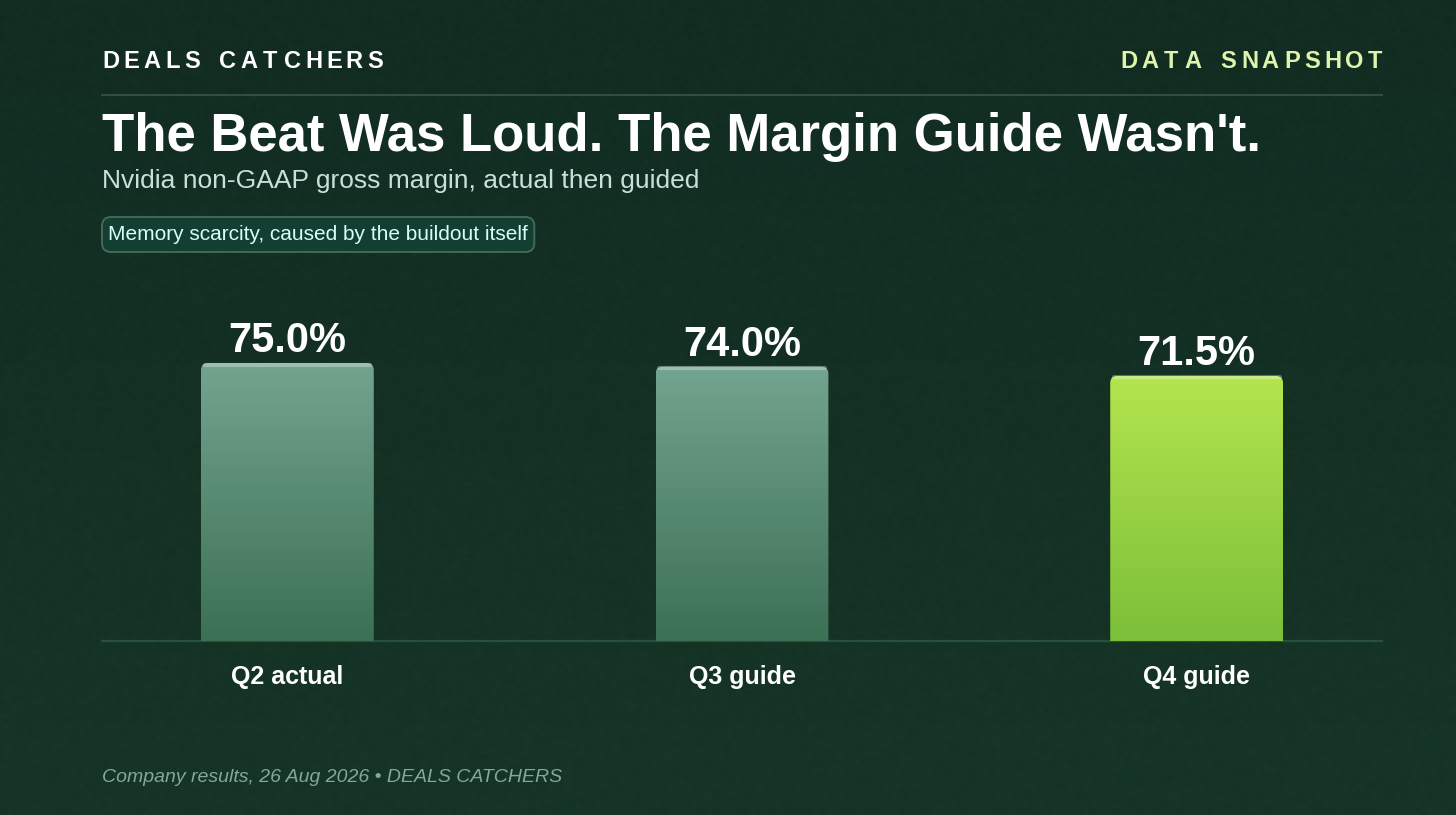
| Nvidia guides gross margin to a 71–72% floor in the fourth quarter, from 75% today, on memory costs. Watch whether other hardware makers follow with the same warning — that is how you tell a company problem from an industry one. |
| The thirty-year yield at 5.337% is the highest since June 2007, and the Treasury has doubled long-end buybacks trying to pull it down. Mortgage rates, annuity pricing and everything long-dated sit on that number. |
| Nvidia’s debt went from $8.5 billion in January to $33.4 billion in July. A company returning $26 billion a quarter to shareholders is also borrowing fourfold. Both facts belong in the same sentence. |
| The Gold Reserve Act still sits on the books. It transferred the nation’s monetary gold to the Treasury and gave the President authority over the dollar’s gold value — a statute written in 1934 that nobody has needed to think about since 1971. |
|
Forget the hot picks — protect what you’ve already built, and remember that the people who set the price never have to break a law to move your money. Because the best trade you’ll ever make is the loss you never took.
— Lee
Thanks for reading. See you tomorrow.
✱ Sources & Disclosures
This is a paid advertisement for Frontieras’s Regulation A offering. Please read the offering circular at https://invest.frontieras.com/
Reservation of the ticker symbol is not a guarantee that we will be listed on the NASDAQ. Listing on the NASDAQ is subject to approvals.
Under Regulation A, a company may change its share price by up to 20% without requalifying the offering with the Securities and Exchange Commission.
Sources* The global market for our products is worth a combined value of over $2.1 trillion — GlobeNewsWire.com, MarketsAndMarkets.com, TransparencyMarketResearch.com, FortuneBusinessInsights.com, MarketResearchFuture.com, PrecedenceResearch.com.
Reservation of the ticker symbol is not a guarantee that we will be listed on the NASDAQ. Listing on the NASDAQ is subject to approvals.
Under Regulation A, a company may change its share price by up to 20% without requalifying the offering with the Securities and Exchange Commission.
Sources* The global market for our products is worth a combined value of over $2.1 trillion — GlobeNewsWire.com, MarketsAndMarkets.com, TransparencyMarketResearch.com, FortuneBusinessInsights.com, MarketResearchFuture.com, PrecedenceResearch.com.