The Stretch Lasted 36 Years. Heirs Now Have Ten.
 |
21 SEPTEMBER 2026
 By Mike Lee
|
Last Wednesday the Fed raised a quarter point — the first hike since 2023. The 10-year tagged 5% and sat back near 4.93%. That is the tape Jeff Brown is driving through: a handful of industrial names already sitting in the default IRA menu, and a market still willing to pay up for whatever those firms ship next.
For anyone living off savings, the demo is not the portfolio. The portfolio is what happens when dollars leave a 401(k) or an inherited IRA this year and have to live in that tape, or in a T-bill, or in the assets the tax code already lets the same account hold.
Three Numbers to Start
4.93% | where the 10-year settled after tagging 5% last week. Cash that leaves an IRA this year can earn that in bills without touching the equity tape. |
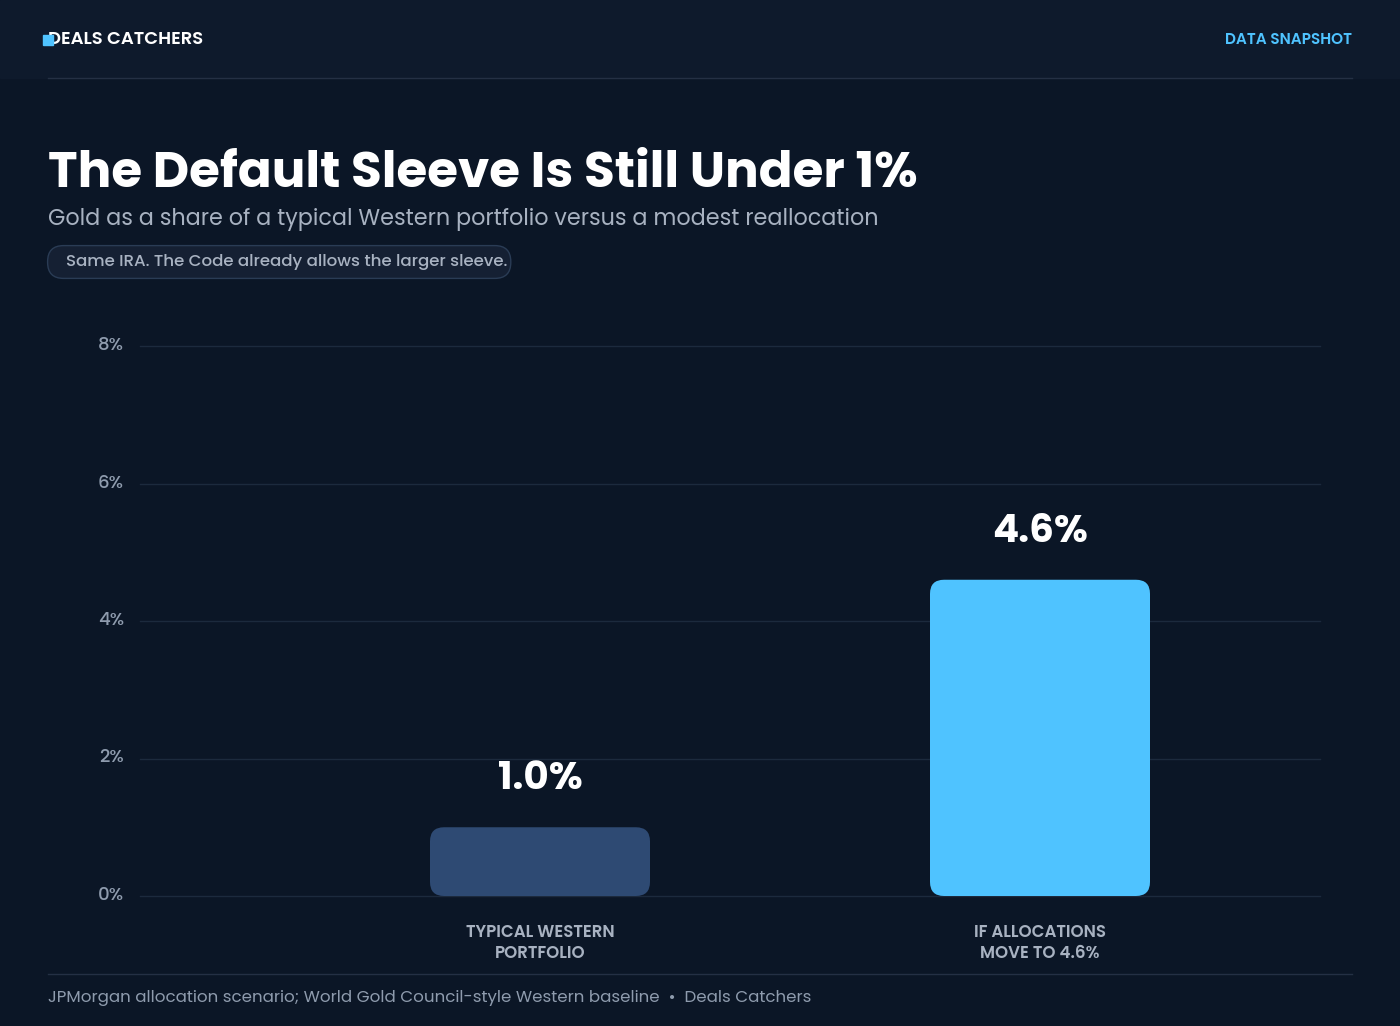
<1% | the gold sleeve still sitting in a typical Western portfolio. The Code has allowed a larger one inside an IRA for decades. Most default menus never offer it. |
101 days | until 31 December, the deadline for 2026 required withdrawals — including the annual inherited-IRA withdrawal if the original owner had already started RMDs. |
The Default Menu Is Not the Code
Most retirement accounts look the way the brokerage app looks: stocks, a bond fund, maybe a target-date sleeve. That is a product menu. Section 408(m) of the Code bans collectibles in an IRA, then carves out specific metal. Gold of .995 fineness qualifies. American Gold Eagles qualify even at .9167. Silver, platinum and palladium have their own floors. Title stays with the trustee. A home safe does not.
McNulty v. Commissioner, 157 T.C. 10 (2021), made the custody line expensive. Coins bought through an IRA and stored at the owner’s house were treated as a distribution. The court taxed the full value. The same ounce is deferred in a depository and ordinary income in a drawer.
A trustee-to-trustee transfer is not a taxable event and has no annual cap. The 60-day rollover — a check in your hand — is allowed once in any 12-month period across all of a person’s own IRAs. An inherited IRA cannot use that window at all. Take a check and the whole amount is a distribution. Retitle first, with the decedent’s name and FBO the beneficiary, or the custodian can treat the move itself as a payout.
Done in that order, the holdings change and the tax basis does not. The open question is the one the default menu never asks: if Western portfolios still keep metal under 1%, and the same IRA can hold a larger sleeve without a new account and without a distribution, is any of it in the account you already have?
|
Two Clocks on the Same Account
The sleeve only matters if the account is still there. For most adult children who inherit a traditional IRA, it will not be — not on the old schedule.
Until 2019 a 50-year-old non-spouse heir divided last year’s balance by 36.2 on the IRS single-life table and called that the required withdrawal. The rest stayed invested, tax-deferred, for more than three decades. The SECURE Act, signed 20 December 2019, ended that stretch for most beneficiaries other than a spouse.
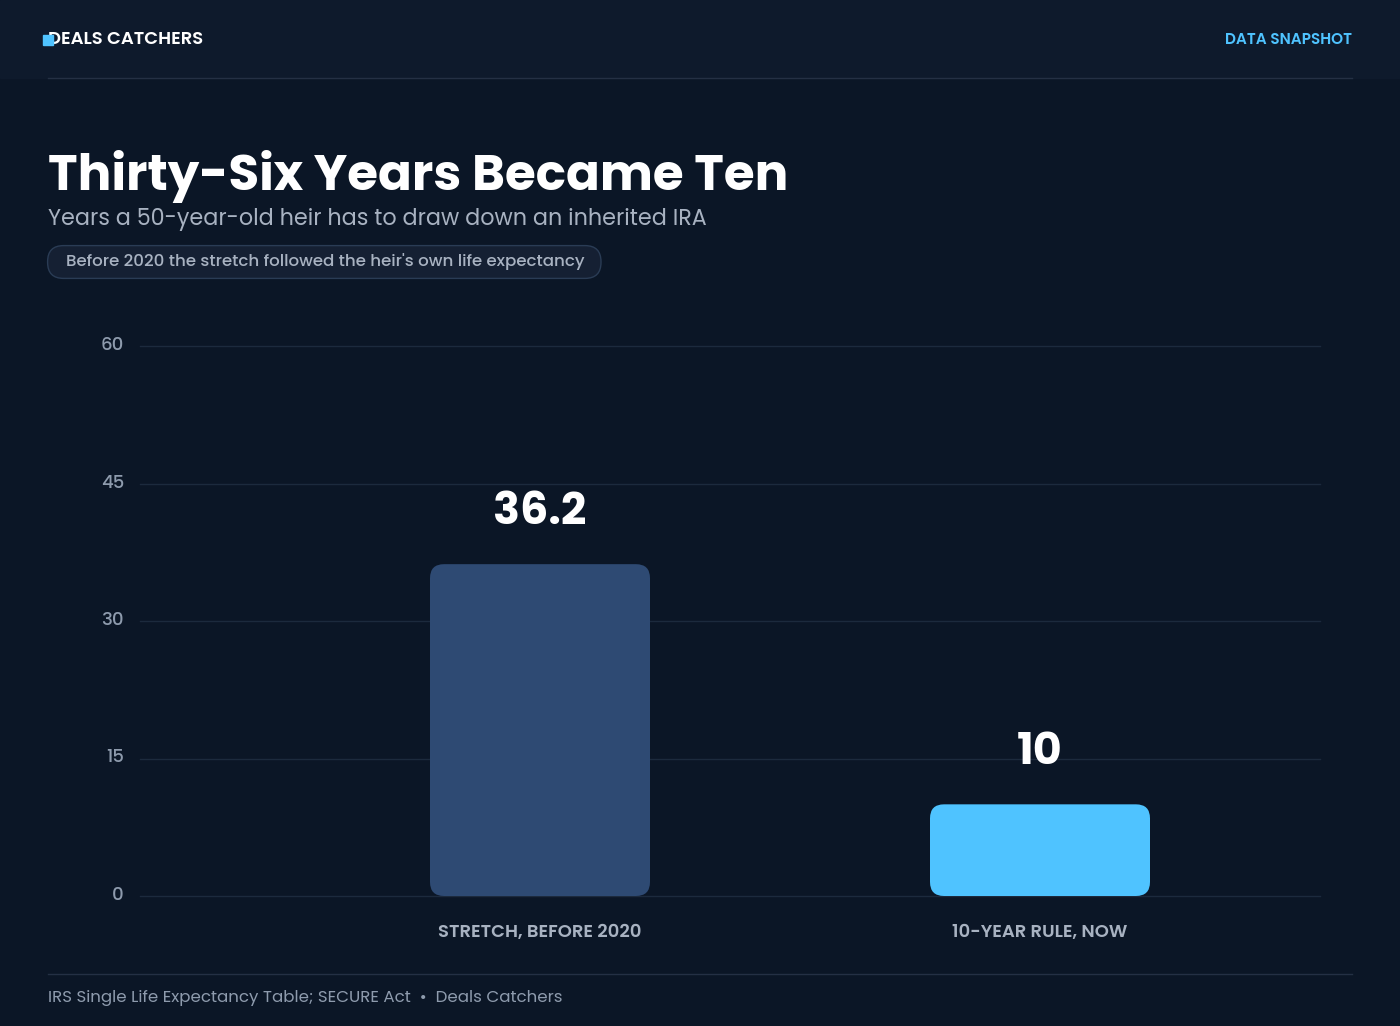
For deaths after 31 December 2019 the outer rule is fixed: the account must be empty by 31 December of the tenth year after death. An IRA inherited in 2021 has to be at zero by the last business day of 2031.
The statute left a second question open: did money also have to come out in years one through nine? Notices 2022-53, 2023-54 and 2024-35 waived the penalty for 2021 through 2024. T.D. 10001, published 19 July 2024, drew the line that actually matters.
There are two clocks. If the original owner died before their required beginning date — 1 April of the year after they turn 73, 75 if born in 1960 or later — a non-eligible heir can sit until year ten and take the balance in one shot. If the owner had already crossed that date, the heir owes a life-expectancy withdrawal every year from one to nine, and still has to empty the account by 31 December of year ten. Skip a year and the shortfall is taxed at 25%, or 10% if fixed inside two years.
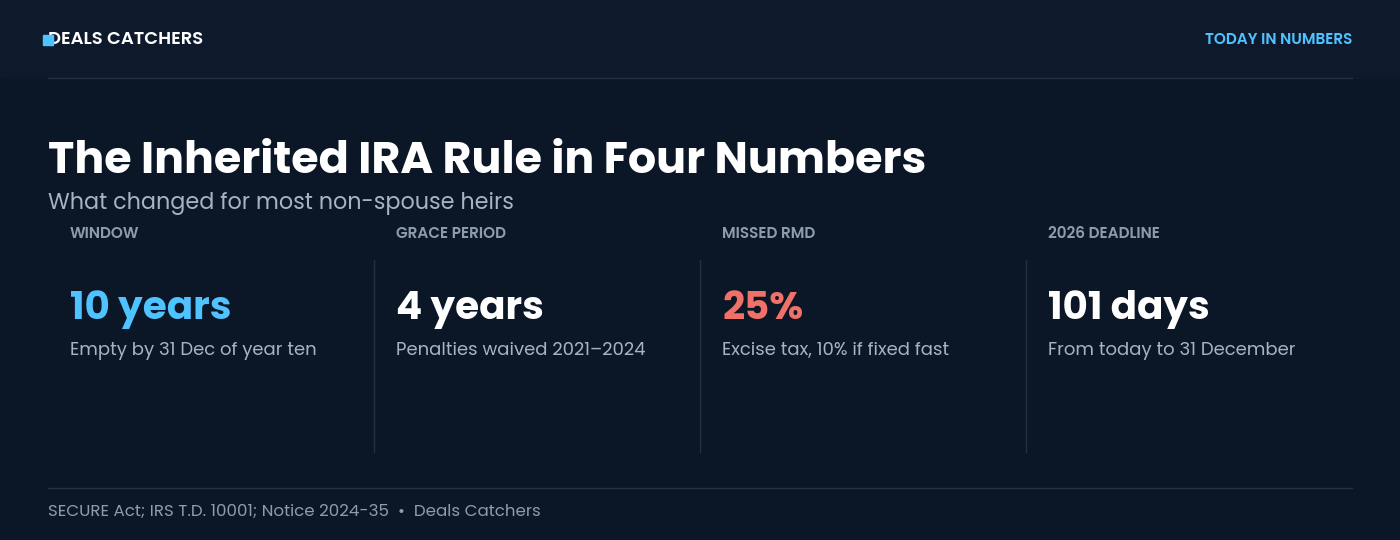
The waived years stay waived. The outer deadline never moved. A 2020 inheritance still has to be empty by 31 December 2030, not 2034. 2026 is the second year the annual rule has teeth.
Five classes still get the old stretch: a surviving spouse; a child of the owner under 21 (the federal age — the ten-year clock starts the year they turn 21); a disabled or chronically ill beneficiary; and anyone not more than ten years younger than the owner. Grandchildren do not qualify just because they are young. An estate named as beneficiary is usually a five-year problem. Everyone else, which is most adult children, is on at least the outer clock.
|
$600,000, Two Tax Bills
Every dollar out of an inherited traditional IRA is ordinary income. No 10% early-withdrawal penalty, at any age. Also no capital-gains rate. The heir pays the ordinary bracket they are in the year the check clears.
Take $600,000. Spread evenly, that is $60,000 a year stacked on salary for ten years. Parked until year ten, it is $600,000 of taxable income in a single filing season.
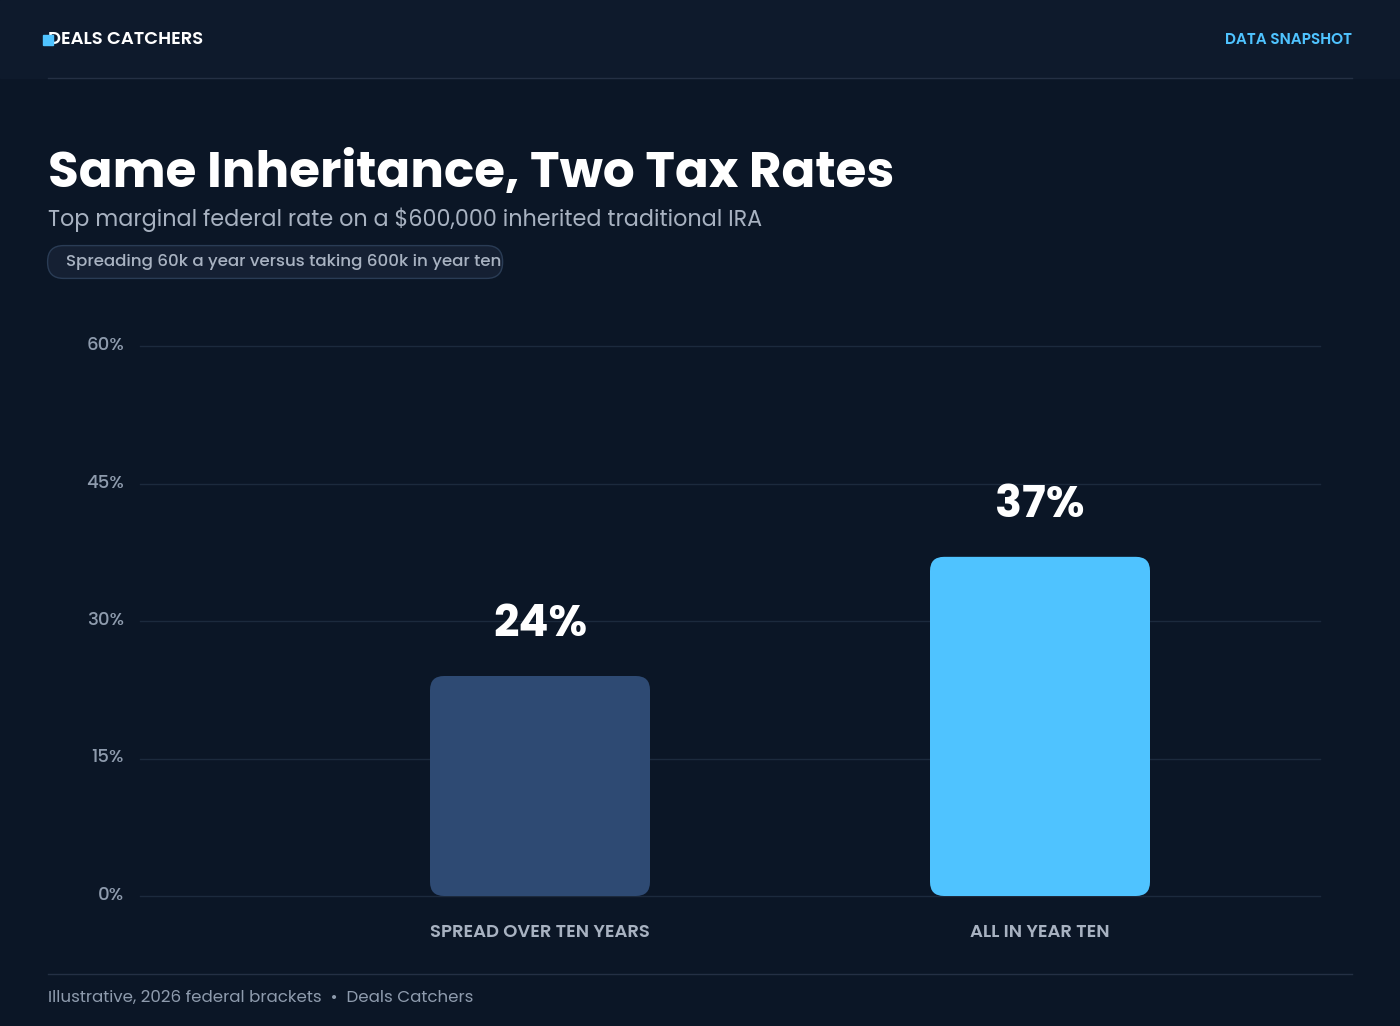
For 2026 the 24% bracket for a married couple runs to $403,550 of taxable income. The 35% bracket starts at $512,451; 37% at $768,701. A single filer hits 35% at $256,226 and 37% at $640,601. Ten slices of $60,000 often stay inside 24% if the household is not already there. One slice of $600,000 walks a single heir through 35% and into 37%. Same balance, same heir, a top rate thirteen points higher. On $600,000 every point of rate is $6,000 before state tax. That is $78,000 of extra federal tax before the 3.8% net investment income tax and two years of Medicare IRMAA.
An inherited Roth still has to be empty by year ten. Because a Roth owner has no lifetime RMDs, most Roth inheritances sit in the pre-RBD branch: no annual withdrawals along the way, and qualified distributions are tax-free if the original Roth is five years old. The same $600,000 left as a Roth is a $0 federal bill.
The moves that change the number are still available before the first forced check: Roth versus traditional while the owner can convert, who sits on the beneficiary form, whether multiple heirs split into separate inherited IRAs by 31 December of the year after death, and whether a qualified disclaimer inside nine months reroutes a share into a lower bracket. After that first distribution, you are sequencing against a W-2. Before it, you are still deciding what the heir inherits.
On the Calendar
Oct | futures still price about a coin-flip on a second hike at the October FOMC, after last Wednesday’s quarter-point. |
This week | Trump meets Gulf leaders. Brent dropped three sessions after Saudi Arabia restored flows through the East-West pipeline. |
31 Dec | last day to take a 2026 RMD, including the annual inherited-IRA withdrawal if the decedent was already in pay status. |
The Bank of Japan lifted its policy rate to a 31-year high. Forced withdrawals this year leave the IRA as taxable cash and then have to live somewhere: bills at 4.93%, the equity tape that is still pricing the next industrial project, or the sleeve the same account was allowed to hold before the check was written.
|
|
101 Days
101 | days to 31 December. If you inherited from someone already in RMD status, this is the second year the annual withdrawal is a live 25% problem. Ask the custodian two questions this week: was the decedent past their required beginning date, and what dollar amount do they show as the 2026 RMD. |
Forget the hot picks — protect what you’ve already built, and know which clock the family accounts are running on before the first forced check goes out. Because the best trade you’ll ever make is the loss you never took. Mike LeeDeals CatchersThanks for reading. See you tomorrow. |
Forwarded this? Get it every morning. |