The Catch-Up Rule Changed on 1 January, and the Trigger Is $150,000
 |
23 SEPTEMBER 2026
 By Mike Lee
sponsored A Rule Change Hit Retirement Accounts |
A massive rule change quietly hit American retirement accounts…  And Wall Street experts are calling it a blatant government cash grab. Congress realized waiting decades to tax retirement savings is no longer an option… So a mandate was passed forcing millions of Americans to pay taxes upfront. America’s top CPA Ed Slott put it bluntly: "Congress went Roth crazy. Why? Because they need the revenue. They get the money upfront." For individuals over 50 trying to max out a 401(k) or IRA… this law could significantly cut into hard-earned nest eggs. Click here to see how SECURE 2.0 impacts retirement accounts (and how to protect savings before it is too late) |
Three Numbers to Start
$150,000 | the wage figure that decides whether your catch-up contribution has to go into a Roth account this year. It reads your 2025 W-2, not your income today. |
$11,250 | the catch-up limit for savers aged 60 to 63, in place of the $8,000 everyone else over 50 gets. |
$8bn | of gold mining deals announced by the middle of this year, across a handful of transactions. |
ad A massive rule change quietly hit American retirement accounts. Congress realized waiting decades to tax retirement savings is no longer an option. See how SECURE 2.0 impacts retirement accounts |
The Catch-Up Rule Changed on 1 January, and the Trigger Is $150,000
Anyone over 50 can put extra money into a 401(k) beyond the standard limit. That extra contribution is called a catch-up, and for most of its life it worked like the rest of the plan: you chose pre-tax or Roth, and most people chose pre-tax.
Section 603 of SECURE 2.0 removed the choice for higher earners. From 1 January 2026, if your FICA wages from the employer sponsoring the plan topped the threshold last year, every catch-up dollar has to go into a Roth account. No deduction now. Tax-free later.
The statute wrote $145,000 in 2022 dollars and indexed it. The figure that applies this year is $150,000, measured against Box 3 of your 2025 W-2. It reads wages from that one employer, not household income, and not the return you will file next spring.
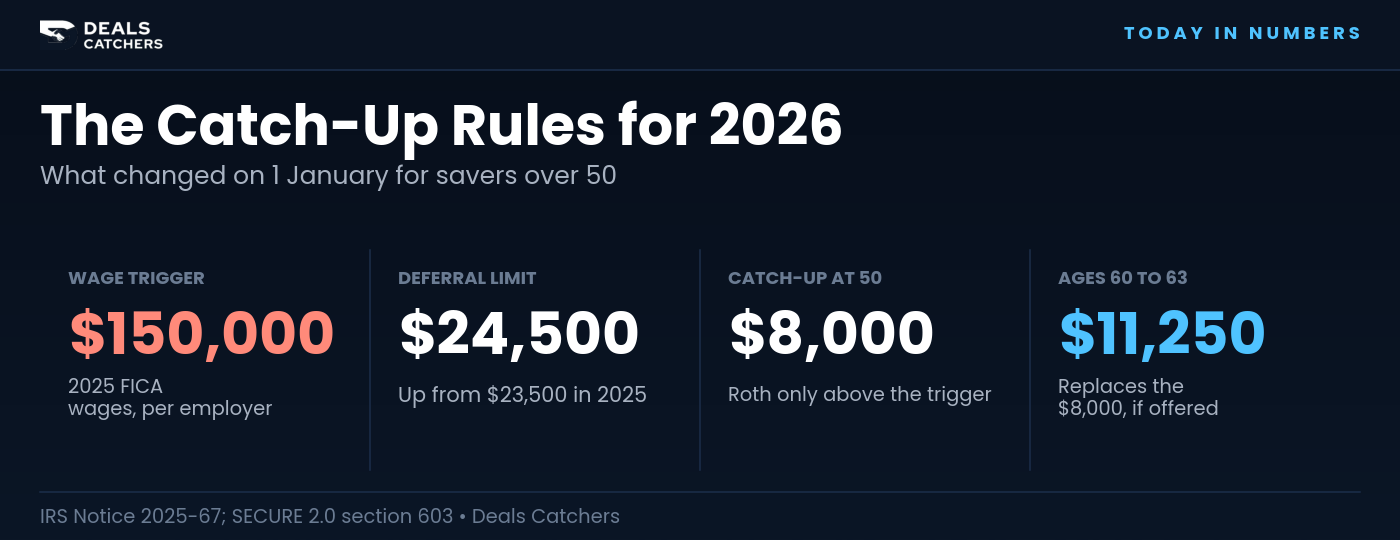
The limits themselves went up. The standard deferral is $24,500 this year, the catch-up at 50 is $8,000, and savers aged 60 to 63 can use $11,250 instead if their plan offers it. That last figure replaces the $8,000 rather than adding to it.
Two operational details matter more than the headline. If a plan has no Roth feature at all, a high earner above the threshold cannot make catch-up contributions this year. And many plans now run a deemed election, which flips your catch-up to Roth automatically once your pre-tax deferrals reach the limit, unless you opt out.
The timing is unusual. Treasury issued the final regulations on 16 September 2025, and they formally apply to tax years after 2026. The statutory requirement still started on 1 January 2026, which leaves this year as a transition run on good-faith compliance. Plan amendments are due by 31 December.
For a saver in a high bracket now who expects a lower one in retirement, the change moves the tax bill forward. For a saver who expects the opposite, it does a favour. Nobody gets to pick which case they are in, and that is the part worth knowing before December.
Newmont Made $7.3 Billion in Cash. The Reserves Did Not Follow
The gold miners are having the year their shareholders waited fifteen years for, and the money is showing up in an unusual place.
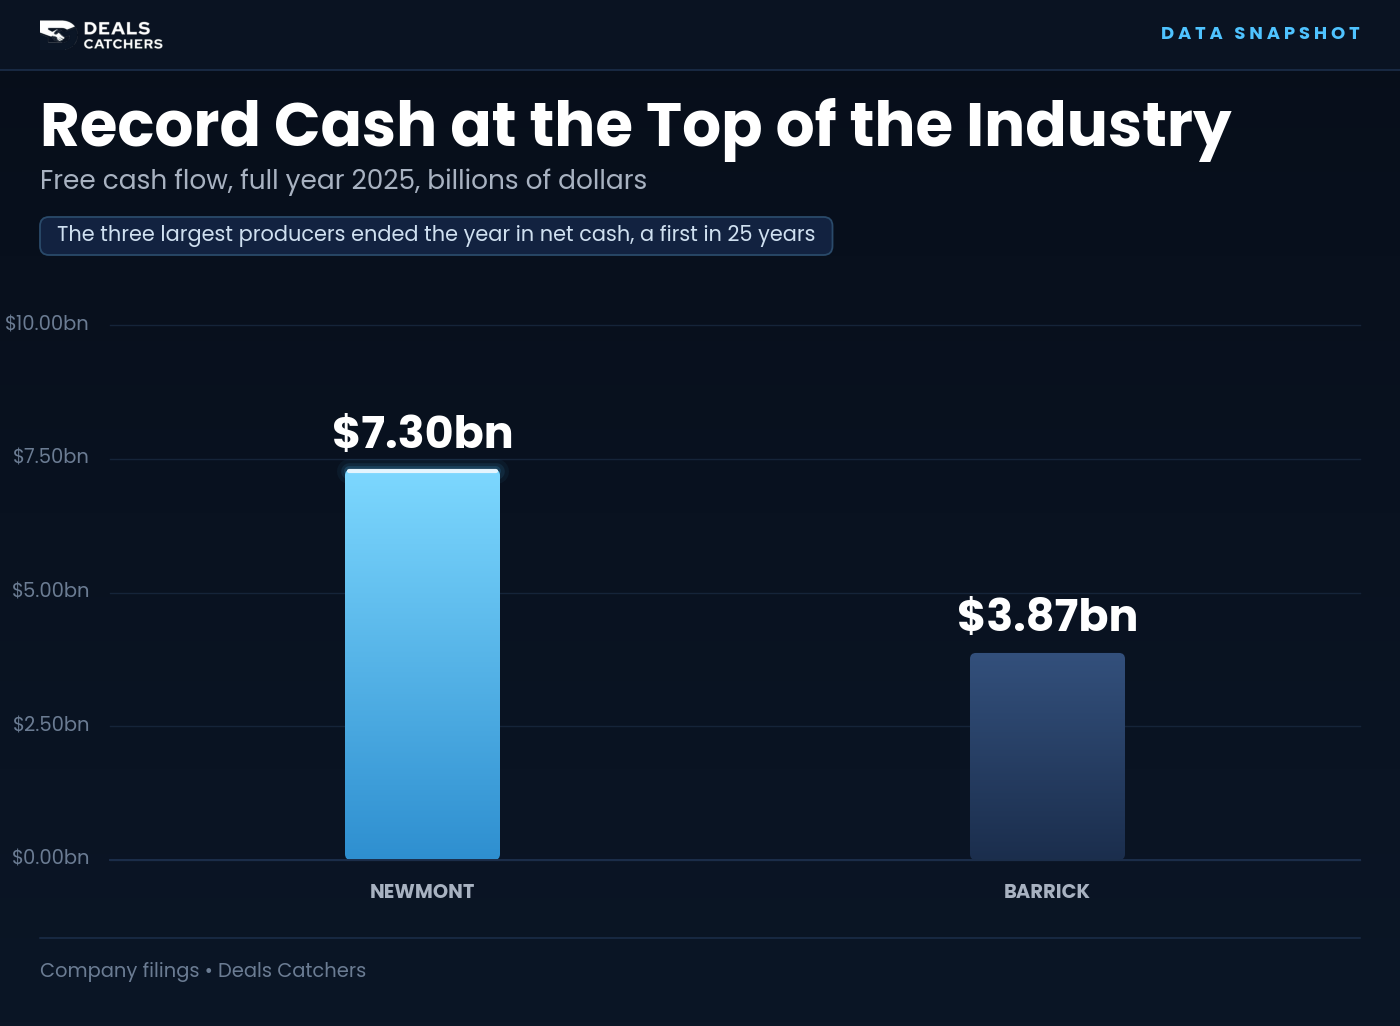
Newmont generated $7.3 billion of free cash flow in 2025, a company record. It paid down $3.4 billion of debt, returned $3.4 billion to shareholders, and finished the year holding more cash than debt. Barrick produced $3.87 billion, close to triple the year before. Agnico Eagle reported $1.335 billion in the second quarter of this year alone.
Taken together, the three largest producers now sit in a net cash position for the first time in 25 years. An industry that has carried debt through every year of this century is suddenly holding a war chest.
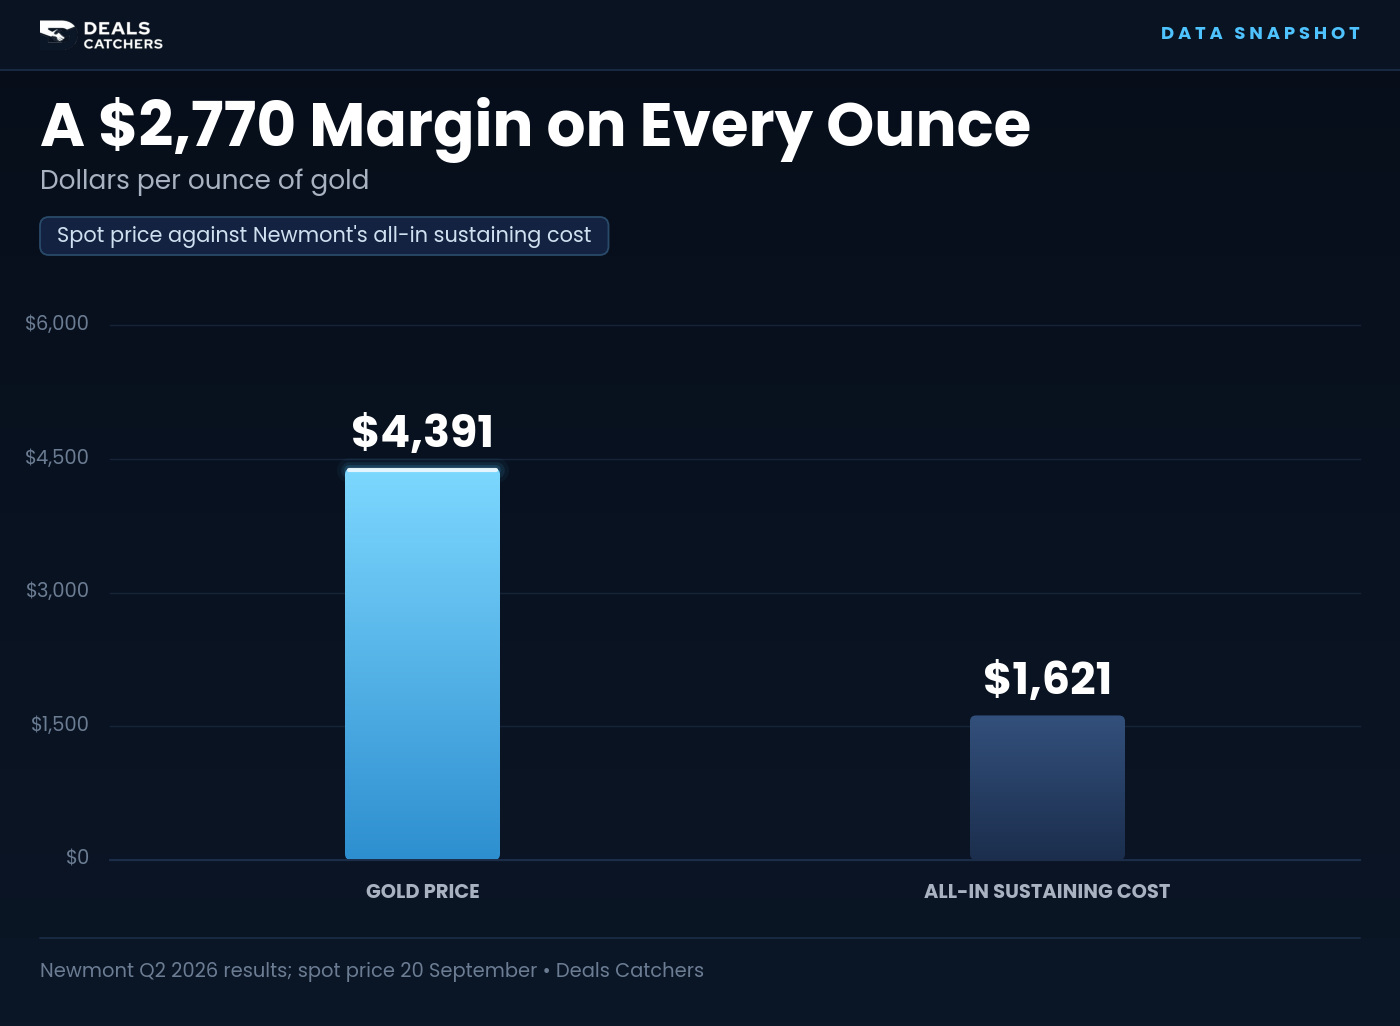
The arithmetic behind it is simple. Newmont reported all-in sustaining costs of about $1,621 an ounce in the second quarter. Gold traded near $4,391 on Friday. Every ounce out of the ground carries roughly $2,770 of margin before tax, and Newmont expects to produce about 5.3 million of them this year.
The problem sits underneath. The majors spent the last fifteen years repairing balance sheets instead of exploring, and their reserve pipelines thinned while they did it. Production depletes reserves every quarter. Discovery does not replace them on that schedule.
So the cash goes shopping. Agnico bought Rupert Resources for $2.1 billion plus two smaller neighbours to lock up a district in northern Finland. Gold Fields took Gold Road Resources. AngloGold paid $2.5 billion for Centamin. By the middle of this year, announced gold deals had passed $8 billion across a handful of transactions.
Buying a developer with a defined resource and a finished feasibility study is faster and cheaper than finding one. There are more than a thousand junior explorers listed, and the majors have both the cash and the reason to work through the list.
sponsored Three Miners Next in Line |
At 4:12 AM Eastern, a single regulatory wire hit the public disclosure servers.  By the time regular trading opened at 9:30 AM, shareholders woke up to an instant 79% jump. No day trading was required. No technical charts to monitor. This overnight repricing happens when cash-heavy mining giants quietly buy out small gold operators while the market sleeps. With the top four gold majors hoarding $18 billion in free cash flow, they have no choice but to go on a buyout spree. Their own production is shrinking every quarter, forcing them to pay 67% to 79%premiums for top-tier junior assets. It has already happened to seven companies in my gold research portfolio — and the buyout wave is accelerating. The window to get in before the next wire drops is closing. See the 3 small gold miners next in line for an overnight buyout |
Two Standards, and Only One Is Called Fiduciary
Anyone who has looked for help with the two questions above runs into the same confusion. Everybody in the industry says they work in your interest. The legal meaning of that phrase depends on the licence.
A registered investment adviser owes a fiduciary duty under the Advisers Act. The duty covers care and loyalty, it runs for the whole relationship, and it obliges the firm to put your interest ahead of its own.
A broker-dealer answers to Regulation Best Interest, which the SEC put in force in June 2020. It requires a recommendation to be in the customer’s best interest at the time it is made, and it attaches to the recommendation rather than to the relationship.
Many firms hold both licences and switch between them depending on the product. The rule is disclosed rather than announced, which is why the paperwork matters.
Three documents settle it. Form CRS runs two pages and states plainly which capacity the firm acts in and how it is paid. Form ADV Part 2 lists fees, conflicts and disciplinary history for an adviser. And both adviserinfo.sec.gov and FINRA BrokerCheck are free and searchable, and will tell you in a minute what a brochure takes an hour to imply.
The fee question is separate from the standard. A percentage of assets, a flat annual retainer and a commission on products create different incentives, and none of them is hidden. Vanguard’s own research puts the value of good advice at up to about three percentage points a year in net return, concentrated in tax placement, rebalancing and stopping people from selling at the bottom.
sponsored Three Signs to Switch Advisors |
 3 Signs You May Want to Switch Financial Advisors Is your financial advisor working in your best interest? Find financial advisors who serve your area, free! For many people, switching financial advisors may seem like an expensive headache, and may put it off, indefinitely. But working with a financial advisor with your best interests in mind could potentially help you find ways to build wealth, safeguard your nest egg against volatile markets, avoid costly tax mistakes and plan your financial legacy for your heirs. If you feel your current advisor is not effectively helping you work toward achieving your financial goals, it may be time to look for someone who can. Whether you are considering switching financial advisors, or working with one for the first time, it’s important to note the potential value an advisor can provide, which may outweigh the costs of their services. SmartAsset’s latest proprietary model reveals that working with a financial advisor could potentially add from 36% to 212% more dollar value to investors’ portfolios over a lifetime, depending on multiple unique, individual factors.1 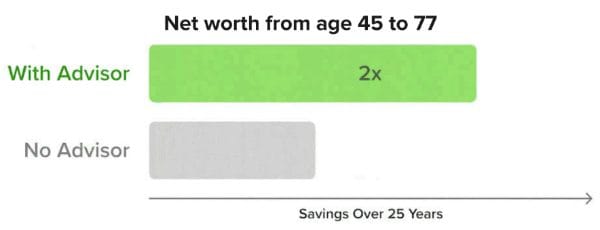 Final lifetime net worth with and without a financial advisor. See disclaimer below. Replacing your advisor doesn’t have to be a hassle or come with high costs. SmartAsset's no-cost tool can help you find and compare vetted fiduciary advisors who serve your area, each legally bound to work in your best Interest. It’s never too late to plan to work toward a comfortable retirement. Get your financial advisor matches today. |
What is Scheduled
Oct | the next Fed meeting. Markets price roughly an even chance of another increase after last week’s first rise since 2023. |
3 Nov | the midterm elections. |
31 Dec | the deadline for this year’s required withdrawals, for Roth conversions counted in 2026, and for employers to adopt the SECURE 2.0 catch-up amendments. |
Those three dates interact. A Roth conversion done in December lands in this year’s income, which sets the Medicare surcharge two years out and sits alongside any catch-up that just became Roth by law. The calendar closes on all of it at once.
ad For individuals over 50 trying to max out a 401(k) or IRA, this law could significantly cut into hard-earned nest eggs. See how SECURE 2.0 impacts retirement accounts |
The Number That Decides It
$150,000 | of FICA wages from one employer in 2025. Above that line, every catch-up dollar you add this year goes in after tax, whatever your plan allowed last year and whatever bracket you expect in retirement. |
Forget the hot picks — protect what you’ve already built, and check which line your own W-2 falls on before December. Because the best trade you’ll ever make is the loss you never took. Mike LeeDeals CatchersThanks for reading. See you tomorrow. |
Forwarded this? Get it every morning. |