Colombia Grew 15% Less Coffee. The Trees Are Still Private.
 |
13 OCTOBER 2026
 By Mike Lee
sponsored From Tree to Shelf |
 A $1,000 stake in Starbucks at its 1992 IPO is worth over $400,000 today. That is a 40,000% return. Enough to fund a retirement. Buy a second house. Cover a decade of not caring what the market did that morning. Wall Street almost missed it. Starbucks priced at $17 a share in June 1992. Split-adjusted, that is about $0.27. The IPO was oversubscribed, but nothing about the pitch screamed 40,000%. Starbucks was a Seattle chain with 165 stores. The biggest coffee brand in America was still Folgers. The investors who bought at $0.27 did not need to be geniuses. They needed to be early. A new coffee empire is being built in the same window right now. Different country. Different model. Same window.  Green Coffee Company owns 45 coffee farms in Colombia. 10 million trees. 10,000+ acres. Vertically integrated from tree to shelf. Own the farm, own the mill, own the distribution. They hold the exclusive US and Canadian grocery rights to Juan Valdez, Colombia's most iconic coffee brand and a 75-year heritage name. Ten-year commercial agreement, locked in. The products are on the shelf at Target, Walgreens, Harris Teeter, and 3,000+ North American stores across 21 states. Revenue grew from $1M in 2021 to $26M in 2025. The company is still private. Reserved NASDAQ ticker. Reg A+ qualified. Open to all investors, no accreditation required. Individual investors can buy in at $1.15, per interest. Minimum $1,001. Up to 20% bonus shares. P.S. Starbucks was a 1992 story. This one is still pre-IPO. Juan Valdez is a licensed brand. The Juan Valdez parties are not sponsors of this offering. This is a paid advertisement for Green Coffee Company’s Regulation A offering. Please read the offering circular at https://invest.greencoffeecompany.com/ Timelines are subject to change. Listing on the NASDAQ is contingent upon necessary approvals, and reserving a ticker symbol does not guarantee a company’s public listing. |
Three Numbers to Start
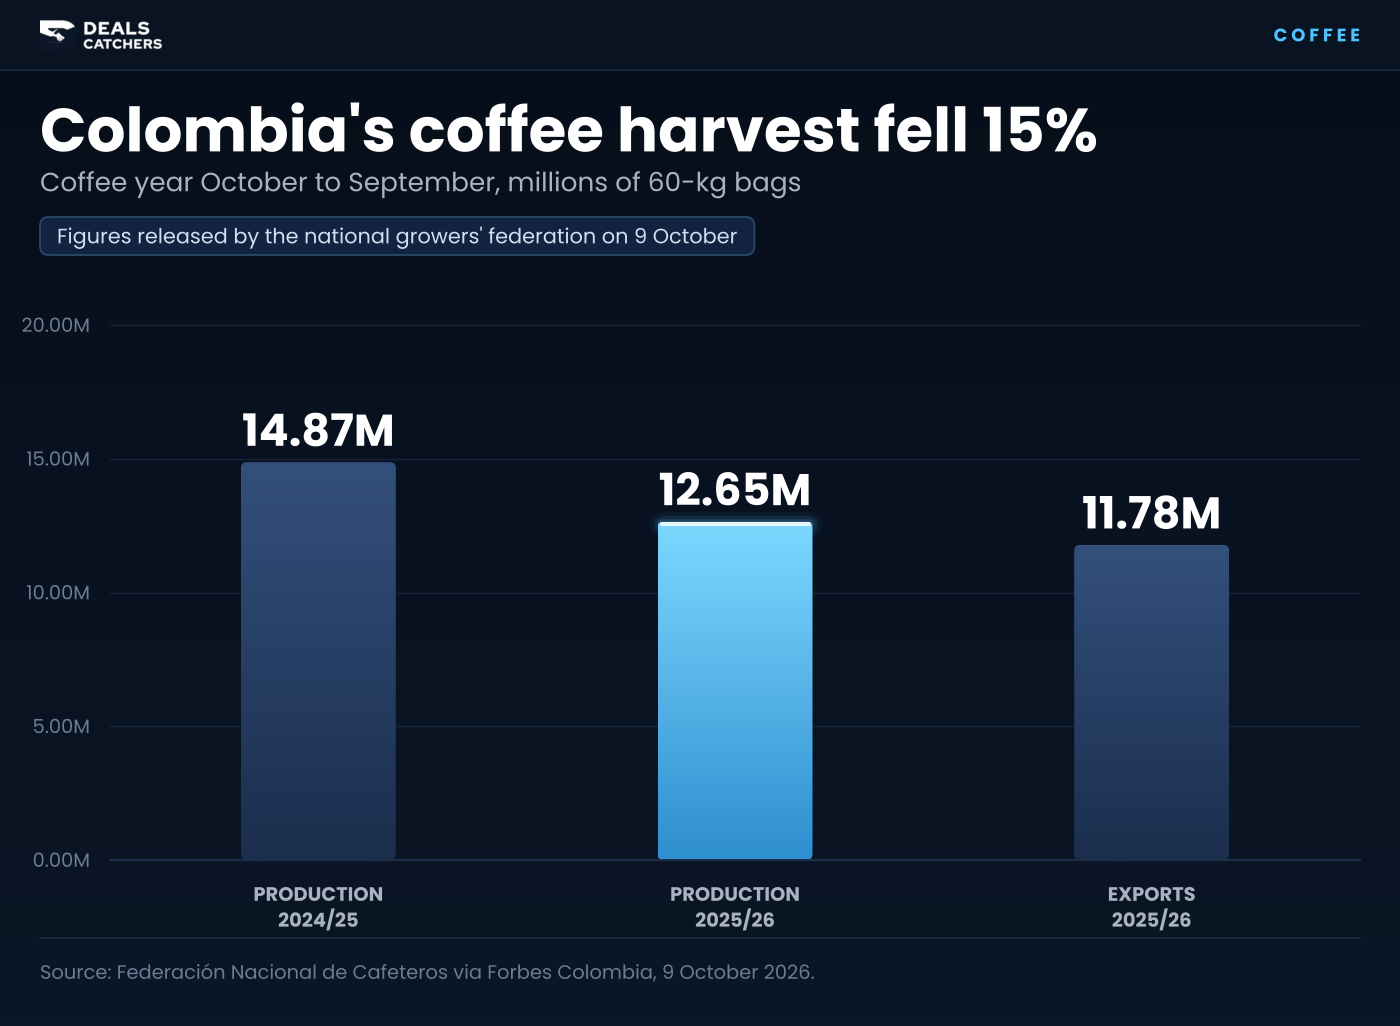
15% | the fall in Colombia’s coffee harvest in the year to September, to 12.65 million bags. |
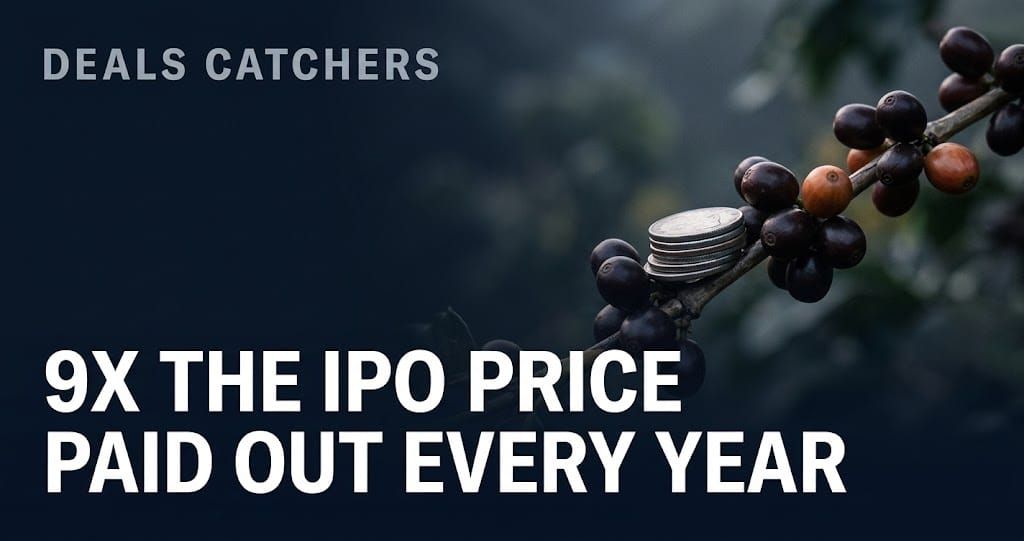
$2.52 | Starbucks’ new annual dividend per share, about nine times its split-adjusted 1992 IPO price. |
$618 | what a gold miner paid in April for each ounce still in the ground. Gold sells for about $4,194. |
ad A $1,000 stake in Starbucks at its 1992 IPO is worth over $400,000 today. A new coffee empire is being built in the same window right now. See the coffee company before its IPO* |
Colombia Grew 15% Less Coffee This Year
Colombia’s National Federation of Coffee Growers closed the books on its coffee year on Friday. The country produced 12.65 million bags between October and September, 15% less than the 14.87 million a year earlier. Exports fell 12%, to 11.78 million bags.
September alone came in 6% above last year, at 1.215 million bags. The year still closed short. A short crop hands the price to whoever owns the trees. An importer that buys green beans on the open market pays the harvest. A company that owns the farm, the mill and the distribution keeps the margin at every step between them.
Green Coffee Company is that stack. Forty-five farms in Colombia, 10 million trees, the US and Canadian grocery rights to Juan Valdez, and product in more than 3,000 North American stores. Revenue went from $1 million in 2021 to $26 million in 2025. The company is still private. The share is $1.15, minimum $1,001, up to 20% in bonus shares. Starbucks was a Seattle chain with 165 stores when it priced at 27 cents. This one is still pre-IPO.
Starbucks Now Pays Nine Times Its IPO Price Every Year
Starbucks raised its quarterly dividend to 63 cents a share last Wednesday, payable on 27 November. That is $2.52 a share a year.
The company went public in June 1992 at $17 a share. Six two-for-one splits since then turn that into about 27 cents. An investor who bought at the IPO now collects about nine times the original cost of each share in dividends every year, before counting the shares themselves.
The buyers who paid 27 cents did not need a forecast of 40,000 stores. They needed to own the brand while it still had 165, and the cheque followed. The same window is the private share at $1.15, with a reserved Nasdaq ticker and a $1,001 minimum. The 1992 story is the dividend. This one is still the entry.
A Gold Miner Paid $618 for an Ounce in the Ground
In April, G Mining Ventures agreed to buy G2 Goldfields in an all-share deal worth $2.2 billion. Analysis published by MineListings put the price at about $618 for each ounce of gold in the ground. Spot gold closed Friday at about $4,194.
The buyers can afford far more. Newmont realised $4,414 an ounce in the second quarter against an all-in sustaining cost of $1,621, a margin of about $2,790 on every ounce. It produced a record $2.2 billion of second-quarter free cash flow, ended June with $9.0 billion in cash and $3.4 billion net of debt, and still has $4.3 billion left on its buyback.
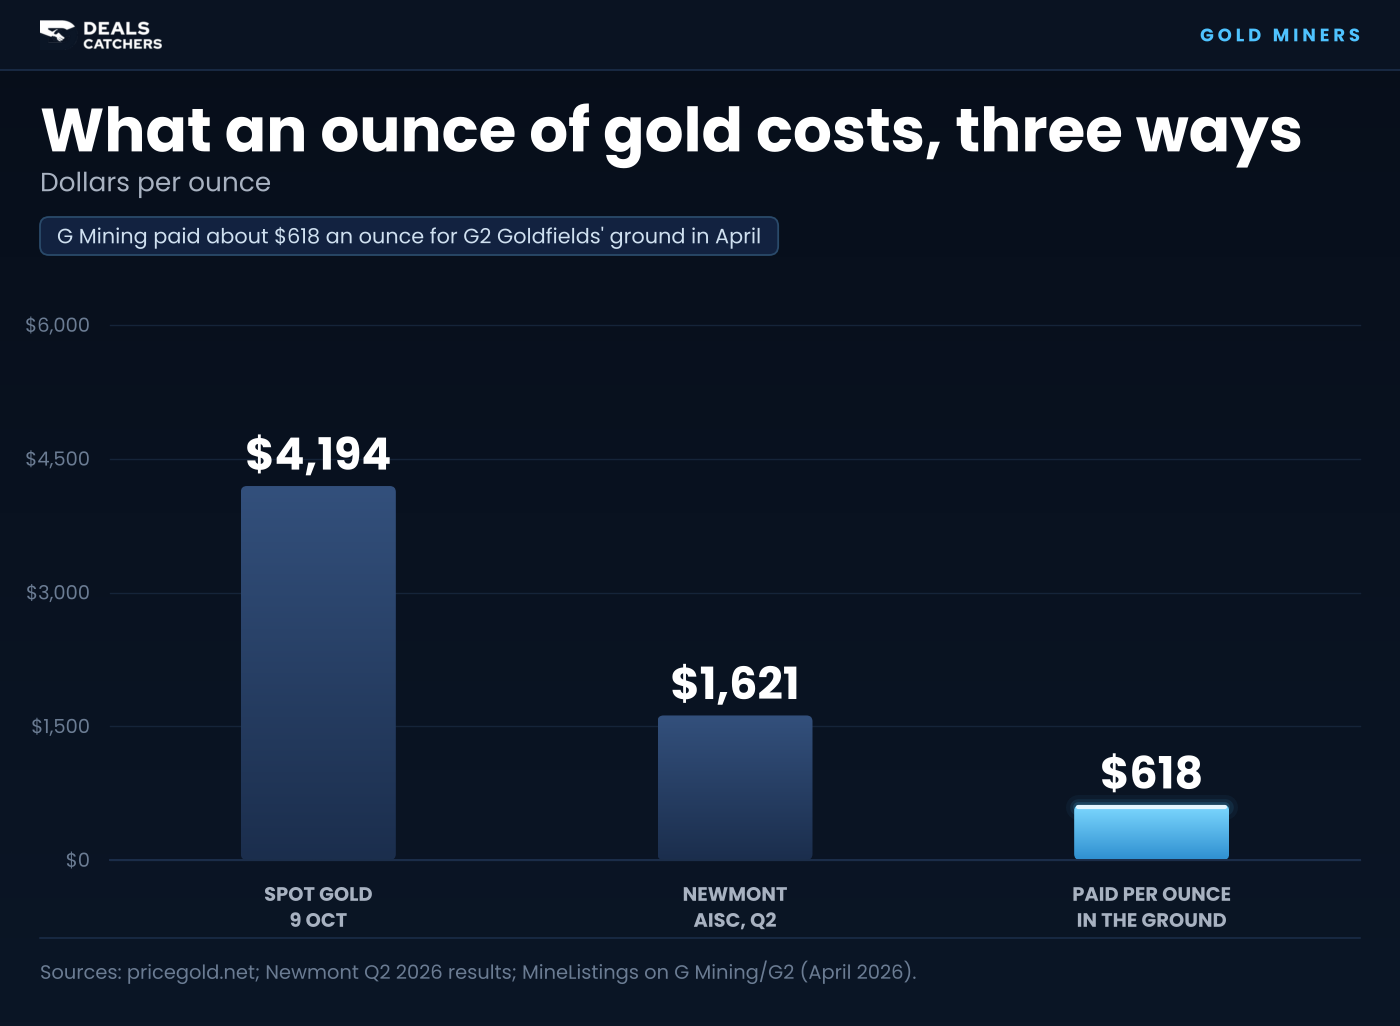
An ounce Newmont mines costs it $1,621 to produce. An ounce bought in the ground from a junior cost G Mining about $618, roughly 15 cents for every dollar of gold at Friday’s price. The majors carry the cash. The juniors carry the ounces at a fraction of spot. That is the shopping list, and the majors are the ones with the till.
Garrett Goggin calls the gap the Golden Anomaly. He tracks the junior producers he expects the majors to buy next, and he names three of them. The gap closes when the cheques start. The three names are the list before that.
sponsored The Golden Anomaly |
 Right now, you can buy a dollar's worth of gold for about 36 cents. That sounds impossible. Here's how it's real. The major gold miners are throwing off record cash flow — even after gold's recent pullback. The four largest have never had this much free cash on hand. Ever. At today's gold price, they're running margins as high as 75% — the most profitable they have ever been. Which hands them a problem. Go here to see the problem — and why the majors are about to go on a shopping spree for the ages. When a major gold miner makes record profits, it does one of two things: hand the cash back to shareholders, or buy the best junior mining assets to secure future production. And here's the piece the market is missing: The best junior assets are still priced as if gold were stuck at $1,800 an ounce — not north of $4,000, where it trades today. So the majors are staring at their own future production shrinking, sitting on record cash, looking at top-tier junior assets trading at a fraction of what that gold is worth at today's price. They don't have a choice. They buy — or their output keeps shrinking until they're out of business. That's how you buy a dollar of gold for 36 cents: you own the junior before the major is forced to pay up for it. The gap between what these assets are worth and what they trade for has a name. I call it the Golden Anomaly. It only appears early in a gold bull market, and it closes fast — usually the moment the majors start writing cheques. So you can pay full price after the gap closes… Or buy the dollar for 36 cents while the Anomaly still exists. My name is Garrett Goggin, CFA, CMT, and it's why Porter Stansberry recently called me: "THE most knowledgeable gold investor in the world." Best, Garrett Goggin, CFA, CMT Lead Analyst and Founder, Golden Portfolio |
Copper Runs Out at Two Metres
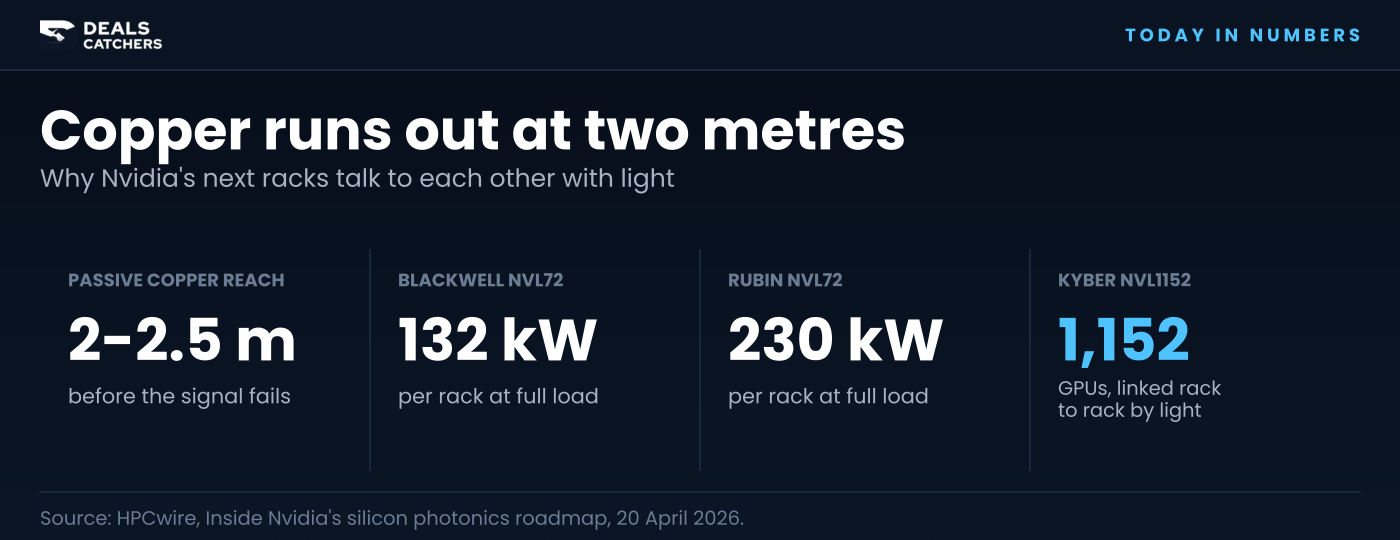
Passive copper cable stops carrying a clean signal at about two to two and a half metres, according to HPCwire’s review of Nvidia’s photonics roadmap. Nvidia’s Blackwell NVL72 rack draws about 132 kilowatts at full load. The Rubin NVL72 draws about 230.
The planned Kyber NVL1152 system joins 1,152 GPUs, sixteen times the processor count of an NVL72, across racks that copper cannot span. Nvidia plans to link them with silicon photonics, using TSMC’s COUPE packaging and more than 20 photonics partners.
Nvidia has been paying for that supply chain since March. The Next Web counted at least $6.5 billion across five photonics deals by the end of May, including $2 billion each in Lumentum and Coherent, a Corning agreement with $500 million in equity warrants, and a stake in Ayar Labs’ $500 million Series E alongside AMD and MediaTek.
The Ethernet version of Nvidia’s co-packaged optics switch, Spectrum-X Photonics, is due to ship this quarter. Copper stops at two metres. The light does not. Jason Bodner names the one stock he believes stands to gain most as light replaces copper inside the AI data centre, and he is giving the name.
sponsored Accelerated AI |
Take a look at this…  It's a radical "light-speed" device that's turning AI as we know it into "Accelerated AI", making it 100 times faster and 100 times more energy efficient. In fact, Jensen Huang, Nvidia's founder and CEO, says this device is shattering the limitations of AI and without it, AI can't scale. If you want to discover what this technology is, why Nvidia is betting billions on it… And the one stock we believe could be the biggest winner when "Accelerated AI" goes mainstream… |
What Is Scheduled
14 Oct | the September consumer price index and the 2027 Social Security adjustment, both at 8:30am Eastern. ASML reports third-quarter results the same day. |
15 Oct | TSMC reports third-quarter results. |
28 Oct | the Fed’s rate decision, six days before the midterm elections. |
ad Starbucks was a 1992 story. This one is still pre-IPO. Invest at $1.15* |
Nine Times the IPO Price
9x | Starbucks’ new annual dividend of $2.52 against its split-adjusted 1992 IPO price of about 27 cents. The early buyers collect that cheque every year. The coffee company with the trees is still private at $1.15. |
Forget the hot picks — own the source before the market prices it. Because the best trade you’ll ever make is the loss you never took. Mike LeeDeals CatchersThanks for reading. See you tomorrow. |
* Juan Valdez is a licensed brand. The Juan Valdez parties are not sponsors of this offering.
This is a paid advertisement for Green Coffee Company’s Regulation A offering. Please read the offering circular at https://invest.greencoffeecompany.com/
Timelines are subject to change. Listing on the NASDAQ is contingent upon necessary approvals, and reserving a ticker symbol does not guarantee a company’s public listing.
This is a paid advertisement for Green Coffee Company’s Regulation A offering. Please read the offering circular at https://invest.greencoffeecompany.com/
Timelines are subject to change. Listing on the NASDAQ is contingent upon necessary approvals, and reserving a ticker symbol does not guarantee a company’s public listing.
Forwarded this? Get it every morning. |